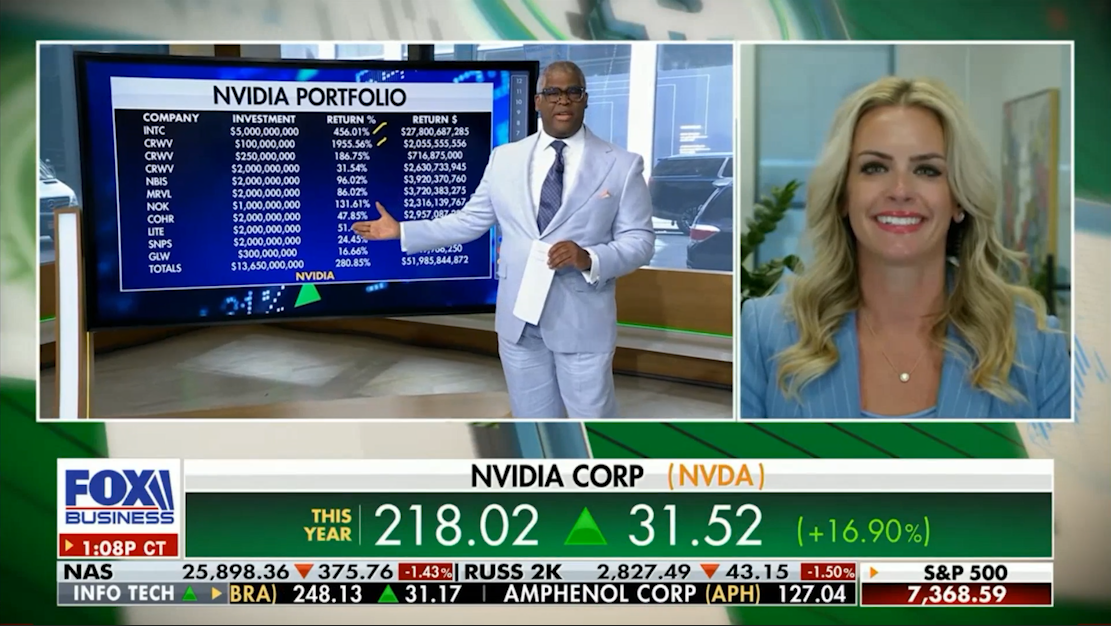
The AI trade keeps evolving.
The last two years have shown just how quickly leadership can shift, from the picks-and-shovels names to software. Lizzie believes the next leg of growth could be driven by agentic AI and inference workloads.
At the same time, AI infrastructure is still one of the market’s biggest drivers. And investors continue rewarding the companies investing heavily in it.
But as the AI mania grows, so does the importance of fundamentals. Not every company will emerge as a long-term winner. Selectivity matters.
Watch Elizabeth Evans, CFP®‘s Fox Business interview with Charles Payne for more insights on the AI trade. ⬇️⬇️
Transcript:
Charles: All right, folks. By the way, my next guest also happens to be a fan of Nvidia. I’m going to bring in now Evans May Wealth Managing Partner Elizabeth Evans. Elizabeth now, and, of course, in addition to being a great investor, Nvidia, you know, which is really amazing. You like it for other reasons, too. You talk about compute, the next leg of AI, and of course, the stock trading at a discount.
Why do you like Nvidia? Why’s this time different?
Elizabeth: Good afternoon, Charles. We do like Nvidia going into the print next week. I think you’ll see another blowout beat-and-raise quarter. So, if investors are underweight Nvidia or under own semis, we do think that there is still continued upside from here. What you’ve heard out of Intel and AMD recently is that the demand for compute far outpaces supply.
And if you look at Nvidia, it’s trading at a discount to its own historical multiple. It has very strong fundamentals. And we see quarter after quarter of upward earnings revisions.
Charles: Elizabeth, what makes this time different though? Because beat-and-raise seems to be par for the course for them. And for the most part, they haven’t been rewarded for it lately.
Elizabeth: Yeah. It’s so true that, you know, really the, it’s not done as well as a lot of the other semis. But if you look at what we’ve seen this earnings season, Goldman expects in 2026 CapEx spending to top $2 trillion, $755 billion of that is coming from hyperscalers. And I also believe that with Nvidia next week, we’ll see that $1 trillion revenue opportunity tied to data centers related to Blackwell and Rubin. I think that there’s more upside there.
Are you concerned that the market is so concentrated? Is there any way that the laggards can help out at some point?
Charles: Let me ask you about the overall market, because from time to time you even mentioned concentration. And you could argue really maybe it’s never been this concentrated. These are the top stocks that contributed to the rally. These are what’s held the rally back. You could argue these five stocks these first five, Micron, Intel, SanDisk, Nvidia, AMD, they’ve done over half the heavy lifting.
Are you concerned that it’s so concentrated? And is there any way that these laggards can help out at some point?
Elizabeth: Market breadth is concerning. It’s the lowest levels we’ve seen in decades outside of the dot-com bubble in mid-2023. But Charles, you mentioned earlier earnings growth and earnings growth hasn’t just been good. It has been phenomenal.
Charles: Right.
Elizabeth: Q1 year-over-year earnings growth is up 27.7%. To put that into context, on March 31st, the expectation was year-over-year earnings growth of 13.1%. So, six weeks later, we’ve more than doubled expectations. Plus, you still have a strong economy.
Cerebras IPO: Are you a potential buyer?
Charles: I’m sorry, but we got a real hot IPO coming on Thursday. Cerebras, it’s an Nvidia competitor. Are you a potential buyer?
Elizabeth: Well, the market’s certainly going to be watching this one closely.
If you look at the last night, the IPO price target moved 150 to 160 bucks a share. They’ve also increased the offering to 30 million shares, and they’re 20 times oversubscribed. So, if you compare it to Nvidia, the valuation is trading at a 45 times trailing 12-month revenue number. And Nvidia has 20 to 25 times.
But it is a super fast growing company. The concern here is that two companies make up 90% of their revenue. They’ve just recently announced a $20 billion contract with OpenAI and an Amazon partnership. So, investors tomorrow will pay for backlog related to OpenAI and Amazon. For us, we’re going to wait and see and follow the price action here in the next month.
Charles: I think I’m going to wait and see, but it will, in my mind, officially set off what could be the hottest IPO summer in history.
Opportunities in the financials sector?
Charles: I got a minute left and I want to just ask you about something. First of all, props. You gave us Citigroup to the audience. You’re up 100% on that. I kind of questioned you when you did it. Props to you. Overall, though, I’m confused. Financials versus the S&P are just in a nosedive. An absolute nosedive. I don’t know why financials are acting so poorly. And ironically you still like two. You like Mastercard and Goldman here. What’s going on?
Elizabeth: Well, Charles, I think a lot of this is attributable to the flattening of the yield curve, which we believe is temporary. We’ve seen this happen in other periods of time and in history. And historically that has been a good buying opportunity. Financials are the most oversold sector in the market year-to-date. So, we do believe that there’s opportunities to pick up good long-term names that are either trading at a discount to the market or their own historical valuation.
Charles: Elizabeth, great stuff and congratulations. You’ve been hot. Talk to you again soon.
Elizabeth: Thank you, Charles.